The 10,000 Yen Threshold and Other Duty Exemptions You Should Know
 By
When foreign alcohol brands plan their first shipment to Japan, small customs exemptions can look like an opportunity to reduce costs. However, these rules have specific conditions. They do not eliminate every tax or regulatory requirement for imported alcohol.
This guide explains duty exemption alcohol Japan rules, the ¥10,000 customs-value threshold, personal-use allowances, and the treatment of commercial samples. Most importantly, it shows foreign brands how to plan their Japan entry costs without relying on exemptions that may not apply.
The ¥10,000 Customs Exemption Explained
What Foreign Alcohol Brands Need to Know
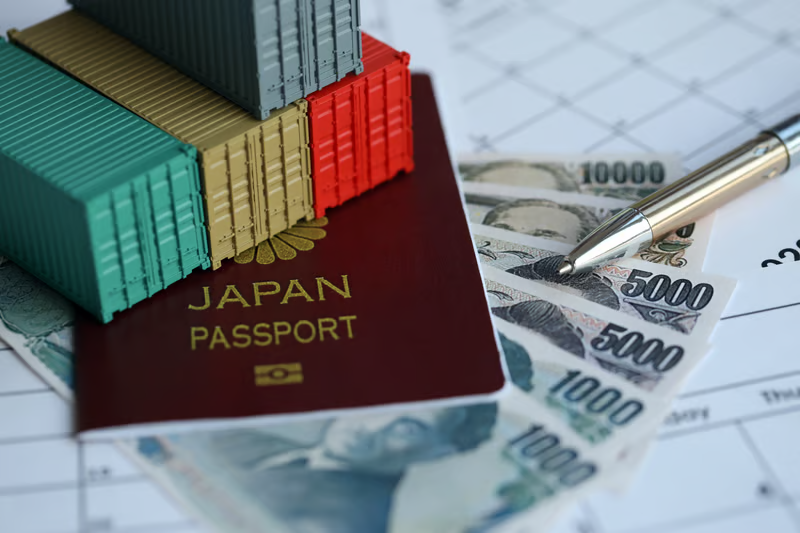
Japan Customs provides an exemption for qualifying imported goods with a total customs value of ¥10,000 or less. However, this rule does not remove every tax on alcohol.
According to Japan Customs, qualifying alcohol imports may receive exemptions from customs duty and import consumption tax when their total customs value does not exceed ¥10,000. Liquor tax still applies, even when the goods qualify for this exemption.
The rule also has specific conditions and exceptions. Therefore, foreign brands should confirm how customs classifies their products before calculating potential savings.
You can review the official guidance here: Japan Customs — Importation of Alcoholic Beverages.
How the Rule Affects Commercial Shipments
A low-value commercial shipment does not automatically qualify for every available exemption. However, it would also be inaccurate to claim that the ¥10,000 rule never applies to alcohol intended for sale.
Japan Customs specifically states that qualifying alcohol imports may receive customs-duty and import-consumption-tax exemptions below this threshold. Nevertheless, liquor tax remains payable.
For example, a small shipment of beer or wine intended for a Japanese distributor still requires careful tax assessment. The importer must determine the applicable customs treatment, liquor tax, and other charges based on the product and shipment.
The Practical Takeaway
Do not build your import budget around the assumption that a small shipment will be tax-free. Instead, separate customs duty, import consumption tax, and liquor tax in your calculations.
This approach gives your business a more accurate picture of the costs involved in entering Japan.
Personal-Use Exemptions for Alcohol
What the Rules Cover
Japan also provides duty-free allowances for individuals importing alcohol for personal consumption. For eligible adult travellers, the standard allowance is three bottles, with each bottle representing approximately 760 ml.
These allowances apply to qualifying personal baggage, not automatically to commercial inventory. Japan Customs also explains that people under 20 cannot claim the alcohol allowance.
See the official rules: Japan Customs — Duty-Free Allowance for Travellers.
Why Businesses Cannot Rely on Traveller Allowances
A foreign brand shipping stock to a Japanese distributor is operating under a different import framework from an individual traveller bringing home a few bottles.
The intended use and circumstances of the import matter. A business cannot turn commercial inventory into personal baggage simply by reducing the quantity.
Therefore, use traveller allowances only when assessing genuine personal imports. For commercial shipments, establish the appropriate import procedures and tax treatment before dispatch.
Alcohol Samples and Customs Requirements
What a foreign brand needs to understand
Product samples sent for evaluation by a prospective distributor, retailer, or buyer occupy a category foreign brands sometimes assume is treated more leniently than a full commercial shipment. In practice, samples of alcohol generally still fall under the standard commercial import framework, since they remain alcohol entering the country regardless of the small quantity or evaluative purpose.
How it plays out in the import process
This means even a handful of sample bottles sent ahead of a formal order typically still needs to move through a licensed importer of record and the standard compliance process — food import notification, appropriate labeling, and the relevant licensing — rather than qualifying for exemption treatment because the quantity is small or the purpose is evaluative rather than immediately commercial.
The practical takeaway
If you’re planning to send samples to a prospective Japanese partner ahead of a full order, coordinate this through your import partner from the start rather than assuming a lighter, exemption-based process applies. This avoids both compliance risk and the frustration of a sample shipment stalling unexpectedly.
When exemptions don’t apply
What a foreign brand needs to understand
The unifying theme across these various thresholds and allowances is that they’re built around personal, non-commercial import scenarios — value-based exemptions for low-value personal or gift shipments, quantity-based allowances for individual travelers. None of them are designed with commercial alcohol import in mind, and none of them scale up to cover a business shipment simply because that shipment happens to be small.
How it plays out in the import process
Every commercial shipment of alcohol into Japan — regardless of size, value, or whether it’s a full order or an initial test batch — moves through the standard commercial framework: licensed importer of record, food import notification, labeling-method notification, and full duty and liquor tax assessment. There’s no smaller-scale version of this process triggered by shipment size alone.
The practical takeaway
Plan your first shipment’s cost and compliance expectations around the standard commercial framework from the outset, rather than researching exemption thresholds hoping one might reduce your burden. It’s a more accurate — and ultimately less disappointing — way to budget.
Avoiding exemption misuse
What a foreign brand needs to understand
It’s worth stating plainly: attempting to structure a genuinely commercial shipment as a personal-use, gift, or low-value import to access exemption treatment isn’t a legitimate cost-saving strategy — it’s a misrepresentation of the shipment’s actual purpose, and it creates real compliance risk rather than avoiding it.
How it plays out in the import process
Customs and quarantine authorities evaluate a shipment based on its actual character and intended use, not simply its declared category. A shipment that’s functionally commercial — intended for resale, arriving as part of an ongoing business relationship — is subject to commercial requirements regardless of how it’s labeled or valued on paperwork.
The practical takeaway
There’s no meaningful upside to attempting this kind of exemption misuse, and genuine downside risk if the shipment’s true character doesn’t match its declared category during review. The straightforward, compliant path is always the better one — both for this shipment and for your standing on every shipment that follows it.
Using exemptions correctly
What a foreign brand needs to understand
None of this means these exemptions are irrelevant or poorly designed — they serve a real purpose for the personal, low-value, and gift-related import scenarios they were built for. It simply means they’re not a resource available to a business bringing product into Japan for commercial sale, which needs to work within the standard commercial import and licensing framework instead.
How it plays out in the import process
For a tax free alcohol import japan outcome to genuinely apply, the shipment needs to actually fall into one of these narrow, non-commercial categories — not be a commercial shipment hoping to qualify. Understanding this distinction early helps you plan an accurate budget and avoid pursuing a path that was never going to apply to your situation.
The practical takeaway
If you’re planning your first commercial shipment to Japan, the cost planning that actually matters is built around standard duty, liquor tax, and consumption tax calculated for your specific product — not around exemption thresholds designed for a different kind of import entirely. A proper cost estimate starts with your actual labels and SKU details, not with hoping an exemption applies.
Understanding what these thresholds actually cover — and confirming that your commercial shipment doesn’t qualify for them — is a useful piece of groundwork before you build out your real cost expectations for entering Japan.
Tell us about your product and SKU range through our contact form, and we’ll review where your brand stands for Japan entry. If you prefer email, you can also reach us at su*****@*******nt.com.